The Author
Born and raised in South Africa, I had everything a child in Africa could wish for. I went to good schools and had many opportunities to explore my talents and dreams. I had loving parents, a mother, and a father living with me under one roof – a privilege for an African child in itself. My parents were initially part of the upper middle class; definitely not wealthy, but we had everything we needed. Both parents were teachers, yes teachers earned a decent living in the 1980s-1990s.
This all changed quite quickly when teachers’ salaries depreciated in relative terms – the increases were consistently smaller than inflation. I would only find out years later that my very own parents found themselves on the slippery slopes of the South African middle class. In my early high school years, I became aware that money did not flow from an eternal fountain, but I started delivering newspapers and had a holiday job for most of my high school years, so I found a way to afford what I needed. Where did it all go so wrong?
The Cycle
The Van Plan is an experiment to see if Financial Independence can be reached within 20 years of first employment in South Africa. Although the high inflation makes it very tough for salary-earning South Africans to achieve Financial Independence even before the age of 65, I also believe that a third-world country like South Africa offers opportunities for extra income. With the correct mindset, good time management and decent financial habits, I believe Financial Independence, Retire Early – also known as the F.I.R.E. movement – is possible. “That is easy to say, but prove it” you might say. Well, that is precisely what this blog is all about. In this blog, I will tell my candid story of how I decided to fix my financial situation and the steps I took to get my journey on track to Financial independence. To make things “fair”, I quit my job in the Engineering industry and started a brand new career in the Financial space. It is not meant as financial advice, but perhaps my story has some valuable tips and tricks that can inspire your story.
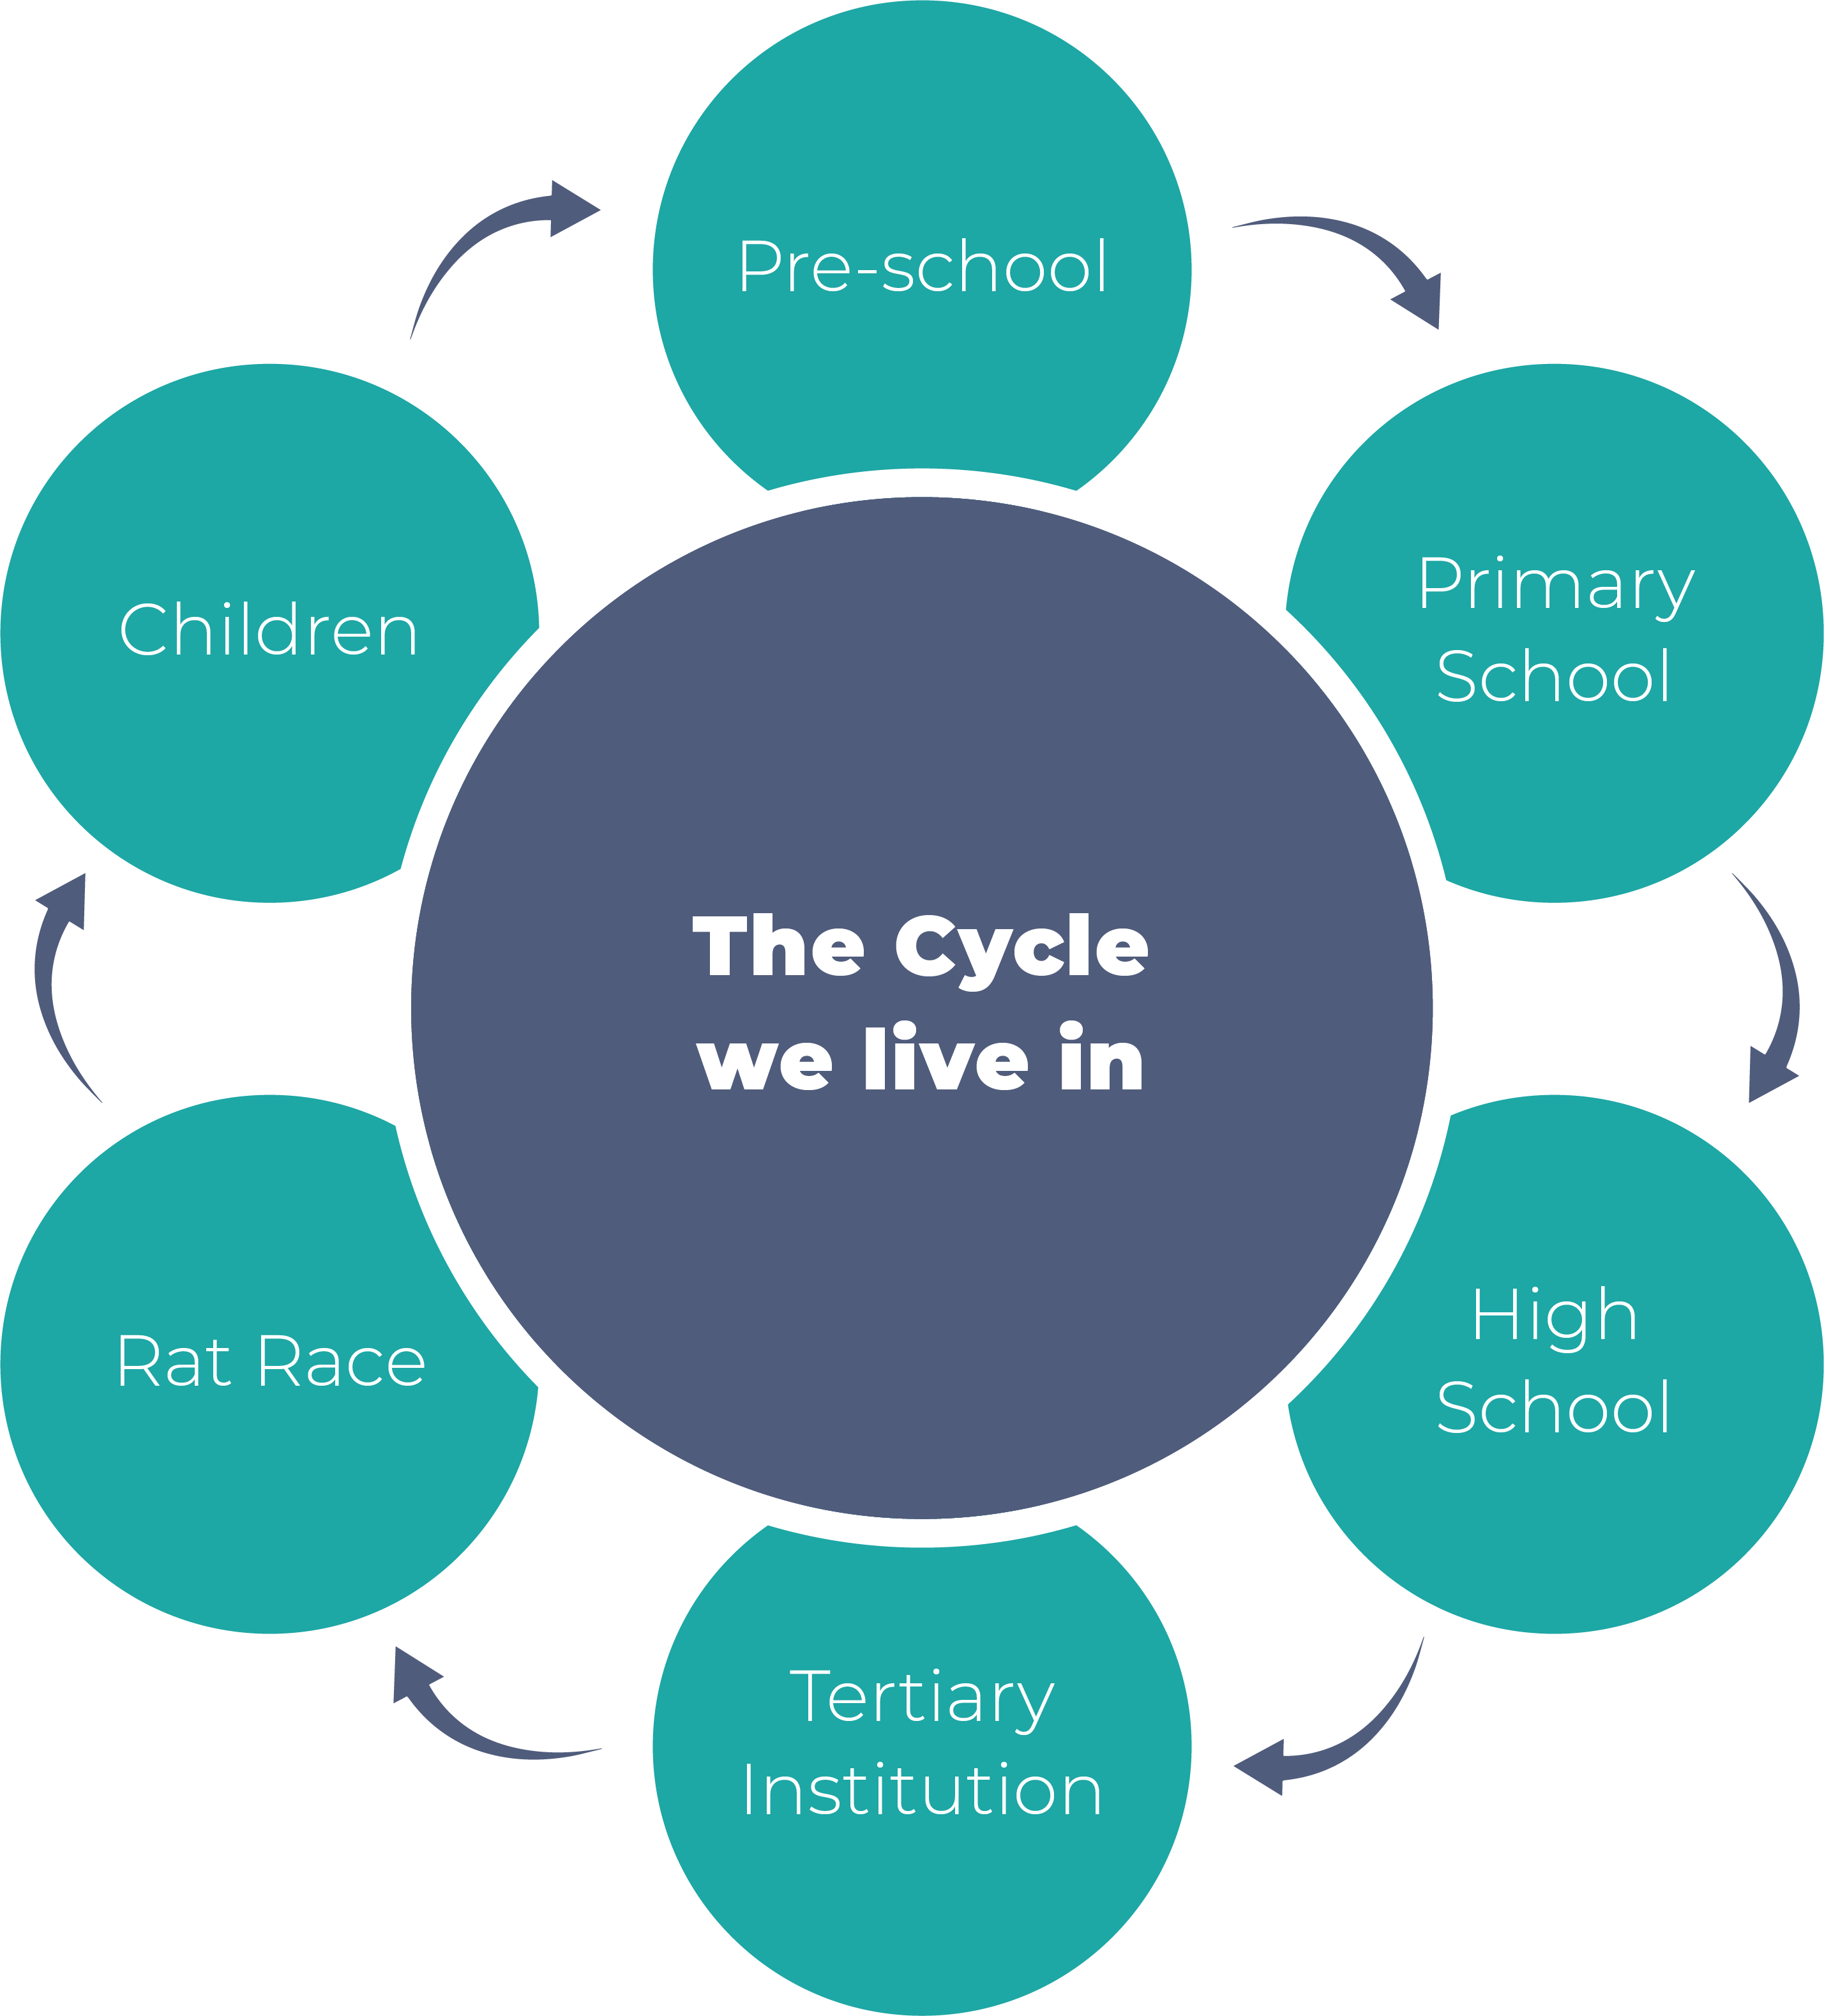
Does this cycle sound familiar?
Does this cycle have a good enough success rate when only about six percent of South Africans can retire at 65 and a meagerly one-and-a-half percent can retire without lowering their lifestyle? Do you also think that the success rate of this cycle confirms that a rethink is necessary? This blog has been written with you in mind.
The Journey
About 7 years ago I saw my parents’ finances for the first time. My father was 60 years old at that stage and had been looking forward to his retirement for a while. The dream has always been a house by the sea and a book in the hand. The reality was very harsh and very sad. It was clear that neither my dad nor my mom, two years younger, could afford not to get an income past the age of 65. Retirement at 65 was simply not an option after almost 45 years of work. I cannot think of a worse realisation than getting your freedom ripped away from you when your freedom is within touching distance.
The three best things that happened to me on my financial freedom journey, happened quite close together and this probably saved me from walking down the same path as my parents. After finding out that my parents’ finances were in shambles (number 1), we lost a big project at work which effectively cut my salary by 20% (number 2). Two months later, I would realise that our new tenant in our rental property is a professional squatter and we would not be getting any rental income for a while (number 3 and a story for another day). “These are all bad things”, you might think. That is exactly the point. We would not have made the drastic changes to our finances if they happened one at a time and spread over an extended period. We would have done nothing unless our debt was getting out of control and I felt it could become my responsibility as the eldest to look after my parents when they cannot work anymore. For some reason, people will ignore bad health until they get a heart attack or keep driving carelessly until they have an accident and somebody gets injured. The scary part is that not all of us get a second chance. Or in my parent’s case, the wake-up call comes too late.
5 years later, in July 2021, I handed in my resignation from my cushy job to experiment with different ways to earn passive income and share my story with the millions of South Africans that have the same fate as my parents, but do not acknowledge it. Within 5 years, I got rid of all my debt (except my home loan) and built an emergency fund for 2 years to give me the time to write this blog among other things. As I write this, I am about to go for an 18km run. I am just about as fit as I’ve ever been and in the best physical shape of at least the last 20 years. The best part is that I am mentally in a positive frame of mind. I have clarity about my goals and do not worry about what other people think of me. I am happy.
I got my wake-up call soon enough, but not everybody will get that wake-up call. Not everybody will start planning for their financial freedom soon enough. That is why I gave up my day job; to help others realise that financial freedom is possible, even at a younger age than 65. The story about my journey and what worked for me starts here.